
Extraordinary S.p.A. resolutions, such as amending the corporate purpose, changing share capital, or converting the company form, require a public deed drafted by a notary. Ordinary shareholder and board decisions, by contrast, usually pass by simple majority of those present or of capital represented, recorded in minutes and transcribed in the corporate books. The first move after any vote is always the same: finalize the minutes, transcribe them in the libri sociali without delay, and call a notary the moment the matter touches the bylaws or capital structure.
TL;DR:
- Most resolutions require proper minutes, timely transcription into corporate books, and, for extraordinary matters, a notarial deed drafted by a notary.
- Ordinary shareholder meetings for S.p.A. need at least half the capital present and a majority vote, while extraordinary resolutions demand higher thresholds, often two-thirds of the capital.
- Remote or written decisions are permitted for S.r.l. quotaholders, but for S.p.A. extraordinary matters, a formal assembly and notarial deed are still required.
- Challenges to resolutions typically must be based on procedural defects or serious nullity issues, but untranscribed resolutions can remain contestable indefinitely.
- Transcription delays and insufficient documentation can expose companies to risks, so procedural discipline and timely filing are critical for validity and enforceability.
Table of Contents
- What Types of Corporate Resolutions Exist Under Italian Law?
- How Do Minutes, Corporate Books, and Notarial Deeds Work?
- What Voting Majorities and Quorums Apply to S.p.A. and S.r.l.?
- Can Resolutions Be Adopted by Written Consent or Remote Meeting?
- When Can a Corporate Resolution Be Challenged or Declared Void?
- What Is the Practical Checklist for Adopting a Valid Resolution?
- How Cerini Notary Office Supports Corporate Resolutions in Italy
- Do Public and Private Companies Follow Different Resolution Rules?
- How Do Resolutions Affect Third Parties, and What Must Be Disclosed?
- What Do Typical Corporate Resolutions Look Like in Practice?
- How Much Control Do Company Bylaws Have Over Resolution Procedures?
- Updating Governance After the 2024–2026 Reforms
- Ready to Formalize Your Company’s Next Resolution in Italy?
- Sources
- FAQ
What Types of Corporate Resolutions Exist Under Italian Law?
Italian company law splits decision-making authority among three organs, and mixing them up is one of the most common (and expensive) mistakes foreign investors make when setting up or running a company in Italy. Knowing which body decides what is the first governance question any director or company secretary should be able to answer without checking the bylaws.
Shareholders’ meetings in an S.p.A. are divided into ordinary and extraordinary sessions, each with a distinct subject-matter list under the Italian Civil Code. The ordinary meeting approves annual financial statements, appoints and removes directors and auditors, and sets their compensation. The extraordinary meeting handles bylaw amendments, capital increases or reductions, mergers, demergers, dissolution, and the appointment of liquidators. Article 2365 of the Civil Code anchors this split, and it is not a matter the bylaws can casually override.
Quotaholders’ decisions in an S.r.l. follow a more flexible model. The Civil Code allows the company’s articles of association to shift substantial decision-making power to written consultation or consent procedures rather than requiring a formal assembly for many matters, something S.p.A.s cannot do as freely for their reserved items. This flexibility is precisely why so many international investors choose the S.r.l. structure when setting up a company in Italy with US shareholders.
The board of directors and delegated bodies decide day-to-day management acts and any matter the bylaws have not reserved to shareholders. A managing director (amministratore delegato) or an executive committee can receive delegated powers, but Italian law and the March 2026 governance reform draw firmer lines around what cannot be delegated, particularly decisions bearing on the company’s solvency and crisis response.
Typical allocation looks like this:
- Shareholders (ordinary): approve financial statements, appoint/remove directors and statutory auditors, set director compensation.
- Shareholders (extraordinary): amend the bylaws, increase or reduce capital, approve mergers or demergers, authorize dissolution.
- Board of directors: approve business plans, authorize significant contracts, oversee delegated bodies, respond to going-concern risks.
- Delegated bodies (if authorized): execute day-to-day management acts within limits set by the board resolution granting delegation.
Listed companies add another layer. Class meetings for holders of special share categories, and the voluntary but near-universal compliance with the Corporate Governance Code, shape how these organs interact. By late 2023 roughly 97% of companies listed on Euronext Milan had adopted that code, which tells you compliance with its recommendations is functionally mandatory even though the code itself is soft law. A listed S.p.A. that departs from Code recommendations without a public explanation faces real market and reputational consequences, even absent a legal sanction.
The bylaws (statuto) can raise quorum or majority requirements for any of these bodies, reserve additional matters to shareholders, or restrict delegation further than the statutory minimum, so no analysis of “who decides” is complete without reading the specific company’s articles alongside the Civil Code.
How Do Minutes, Corporate Books, and Notarial Deeds Work?
Every valid resolution in Italy rests on a paper trail, and the strength of that trail determines whether the decision survives a later challenge. Getting the formalities right at the moment of the vote is far cheaper than fixing them afterward.
What must the minutes contain?
The minutes (verbale) need to identify the chair and secretary, record who attended (in person, by proxy, or remotely), state the agenda items discussed, and capture the precise roll call: how many votes were cast for, against, and abstaining on each resolution. A minute that simply states “the resolution was approved” without a vote breakdown is a weak document if anyone later disputes the outcome. For S.p.A. shareholders’ meetings, a notary frequently drafts the minutes even for ordinary sessions in practice, though the law only mandates a notarial deed for extraordinary matters.
Why transcription in the libri sociali matters
Once minutes are signed, they must be transcribed into the company’s corporate books, the libri sociali, without delay. This is not paperwork for its own sake. A Court of Milan ruling (Judgment no. 91/2025) clarified that failing to transcribe a shareholders’ resolution into the decision book is a formal irregularity. It does not, by itself, invalidate the resolution. But it does something arguably worse from a risk perspective: it prevents the statutory time limit for challenging that resolution from ever starting to run. A resolution that sits untranscribed can remain exposed to challenge indefinitely, long after everyone assumed the matter was settled.
When is a notary or public deed mandatory?
The passage contains the word “delle” in the suggested corrections, but it does not appear in the original text provided. Since there is no instance of “delle” in the original passage, no correction is necessary. All terms and phrases appear correct in context.
Chamber of Commerce certificates or plain minute extracts are sufficient for most ordinary business. Anything reshaping the corporate structure itself, however, moves into notarial territory, a distinction covered in more detail in our guide to notary requirements for starting a company in Italy.
Electronic records: what current practice allows
Digital transcription and electronic signatures on minutes are now widely accepted in practice, and many companies keep both a digital record and the traditional bound physical register. That dual approach is not just belt-and-suspenders caution. Practitioners commonly find that a physical libri sociali left unnumbered or undated becomes a genuine liability in timing disputes, since a judge examining when a resolution was actually recorded needs a document that itself proves its own date.
Pro Tip: Number and date every page of the physical libri sociali as you go, even if you also maintain a digital copy. An undated digital file can be recreated after the fact; a properly bound and paginated physical register is far harder to contest.
What Voting Majorities and Quorums Apply to S.p.A. and S.r.l.?
Getting the math right on quorum and majority is where most disputes over Italian corporate resolutions actually start, because the default statutory rules shift depending on whether the meeting is ordinary or extraordinary, and the bylaws are free to raise the bar further in most cases.
For S.p.A. ordinary shareholders’ meetings, the default rule requires the presence of shareholders representing at least half the share capital, with resolutions passing by absolute majority of the capital represented at the meeting, unless the bylaws set a different threshold. On a second call, quorum requirements typically relax, though the bylaws control the exact figures.
Extraordinary S.p.A. resolutions demand more. Bylaw amendments, capital changes, and mergers generally need a qualified majority, and for certain listed-company matters the law or the bylaws set the bar at two-thirds of capital represented at the meeting. This is precisely why extraordinary items get bundled with notarial deeds: the stakes and the procedural rigor rise together.
S.r.l. quotaholder decisions follow a parallel but distinct logic. The default majority for ordinary decisions is based on quota percentages rather than meeting attendance, and the articles of association routinely deviate from the statutory default to require supermajorities for specific categories of decisions, such as admitting new quotaholders or approving related-party transactions.
Key mechanics to check before calculating any vote:
- Proxies: Italian law permits proxy voting in most cases, but bylaws can cap the number of proxies a single representative may hold, and listed companies face additional proxy solicitation rules.
- Abstentions: typically count toward quorum (presence) but not toward the majority calculation itself, though the bylaws’ precise wording controls this.
- Second-call meetings: often carry lower quorum thresholds than the first call, a mechanic bylaws use to prevent deadlock when attendance is thin.
- Class votes: where special share categories exist, a resolution affecting their rights may need a separate class meeting majority in addition to the general shareholders’ vote.
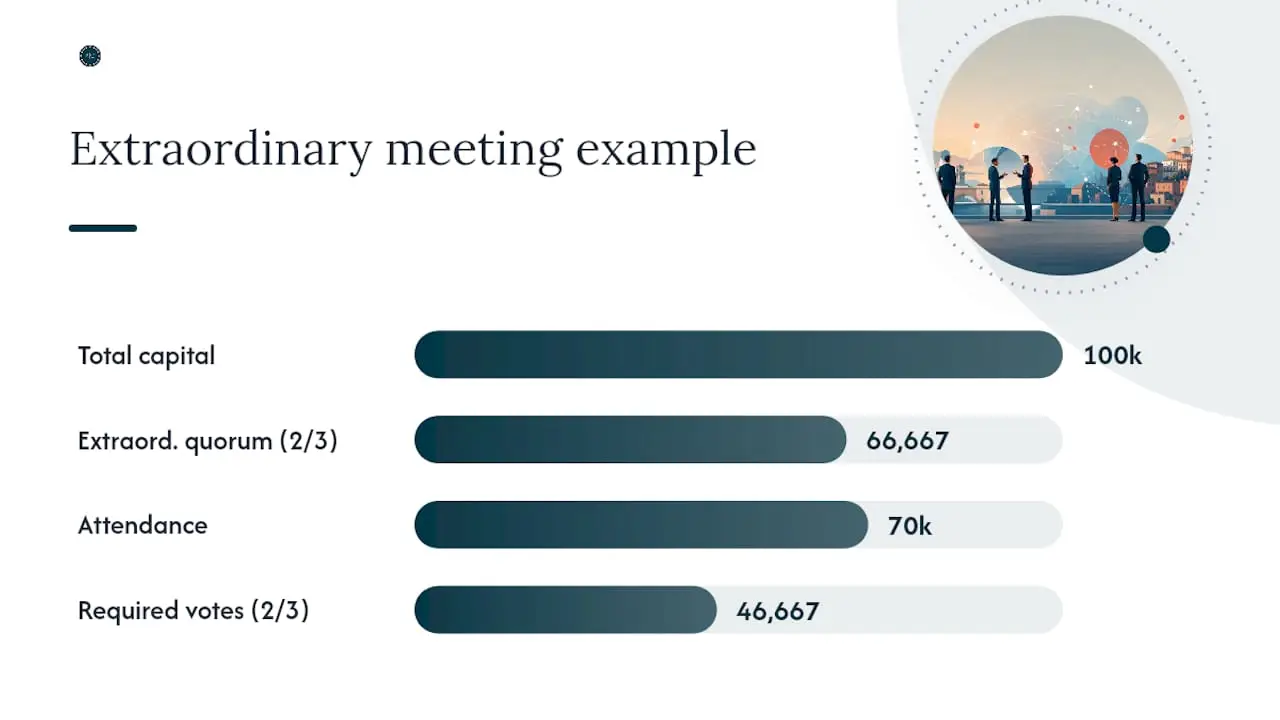
A worked example clarifies the mechanics: an S.p.A. with 100,000 shares calls an extraordinary meeting to amend its corporate purpose. If the bylaws set the extraordinary quorum at two-thirds of capital and the majority at two-thirds of capital represented, a meeting attended by holders of 70,000 shares clears quorum, and the resolution needs votes representing at least 46,667 shares (two-thirds of 70,000) to pass. Miss either threshold, and the resolution is void from the start, not merely voidable. Before any extraordinary vote, pull the bylaws and confirm the exact clause language rather than assuming the statutory default applies, since foreign shareholders in particular often discover the company’s articles have quietly raised the bar well above the Civil Code minimum.
Can Resolutions Be Adopted by Written Consent or Remote Meeting?
Italian law lets companies skip a physical meeting for many decisions, but the permission is narrower than most foreign directors assume, and using it incorrectly can void the resolution entirely.
S.r.l. quotaholders benefit from the most flexibility. The Civil Code allows the articles of association to authorize decisions through written consultation or express written consent instead of convening a formal assembly, provided the bylaws spell out the procedure and every quotaholder receives clear, timely information about the proposal. S.p.A. shareholders have far less room to maneuver: ordinary matters can sometimes proceed through simplified procedures if the bylaws allow it, but extraordinary matters, particularly those requiring a notarial deed, cannot be resolved by written consent alone. The notary still needs an assembly (even a remote one) to draft and authenticate the deed.
Remote and hybrid meetings are now standard practice across Italian companies, accelerated by pandemic-era rules that outlasted the emergency itself. Running one safely, especially with participants dialing in from outside Italy, calls for a defined protocol:
- Send notice early, specifying the platform, dial-in details, and any identity-verification steps participants must complete before the meeting opens.
- Verify identity at login, particularly for foreign shareholders attending through a proxy or power of attorney rather than in person.
- Confirm connectivity and voting mechanics at the start of the meeting, and record any technical interruptions in the minutes as they occur.
- Capture the full roll call electronically, timestamping votes so the record shows exactly when each participant voted and how.
- Preserve the recording and chat logs alongside the signed minutes, since these can become critical evidence if a participant later disputes what was said or decided.
Pro Tip: If a shareholder is attending remotely from abroad and cannot appear before an Italian notary for an extraordinary resolution, a properly executed and apostilled power of attorney prepared in advance is almost always faster than trying to arrange overseas notarial cooperation on short notice.
When Can a Corporate Resolution Be Challenged or Declared Void?
Two distinct remedies exist under Italian law, and confusing them is a common and costly error for anyone contesting a resolution.
Annullability (annullabilità) applies to resolutions adopted in violation of the law or the bylaws through a procedural defect, such as a notice failure, a quorum miscalculation, or a shareholder voting despite an undisclosed conflict of interest. Only shareholders who did not vote in favor, absent shareholders, directors, or statutory auditors can bring this action, and it must generally be filed within ninety days of the resolution date or its transcription, depending on the company type.
Nullity (nullità) is reserved for more serious defects, resolutions with an unlawful or impossible object, or those adopted without any notice at all to entitled participants. Nullity actions can typically be brought by anyone with an interest, including third parties, and the time limits are longer, sometimes running three years from transcription.
This is where the transcription question from earlier becomes critical again. Because the challenge clock for many actions only starts running once a resolution is properly transcribed into the libri sociali, an untranscribed resolution never triggers the countdown. The Court of Milan’s 2025 analysis makes clear this creates a genuinely awkward position: the resolution itself may be perfectly valid on the merits, yet remain permanently open to attack simply because nobody logged it correctly.
The defects that most often sink a resolution in practice include:
- Defective notice: shareholders not given the legally required advance notice period or notified through the wrong channel specified in the bylaws.
- Quorum miscalculation: counting abstentions or non-voting shares incorrectly when determining whether the meeting was validly constituted.
- Undisclosed conflicts of interest: a director or shareholder voting on a matter where personal interest was not disclosed as required.
- Missing or incomplete minutes: a vote tally that cannot be reconstructed from the record, undermining the resolution’s evidentiary basis.
Arbitration has become a more common route for resolving these disputes outside court, with usage climbing by roughly 59% in recent years, though it works best for shareholder disputes over valuation or contractual matters rather than nullity claims touching third-party interests. The most effective defense against any of this remains procedural discipline: transcribe promptly, publish required notices exactly as the bylaws demand, and retain every piece of supporting evidence, from attendance sheets to proxy forms, well beyond the minimum retention period.
What Is the Practical Checklist for Adopting a Valid Resolution?
A resolution that survives scrutiny later is built correctly from the first notice onward, not patched together after the fact. Breaking the process into three phases keeps nothing from slipping through.
Before the meeting:
- Draft the agenda precisely, since resolutions on matters not listed are vulnerable to challenge.
- Send notice within the deadline and through the channel the bylaws specify.
- Prepare proxy forms and confirm the shareholder register is current.
- Book a notary in advance for any extraordinary item, since notarial calendars fill up faster than most first-time founders expect.
During the meeting:
- Open with a clear statement identifying chair, secretary, and quorum confirmation.
- Record the roll call for every resolution separately, not just the meeting as a whole.
- Flag and document any conflict-of-interest disclosure the moment it arises.
- Have the notary attest extraordinary resolutions on the spot where a public deed is required.
After the meeting:
- Transcribe the minutes into the libri sociali immediately, not at month end.
- File the required documents with the Registro delle Imprese within the statutory deadline.
- Request legalized abstracts or an apostille if the resolution needs to be used or recognized abroad.
| Formality question | Ordinary S.p.A./S.r.l. matter | Extraordinary S.p.A./S.r.l. matter |
|---|---|---|
| Notary required? | Generally no | Yes, public deed |
| Chamber of Commerce filing? | Often yes, within statutory deadline | Yes, filed by the notary |
| Transcription in libri sociali? | Yes, always | Yes, always |
| Apostille/legalized abstract needed? | Only if used abroad | Common for foreign shareholder use |
Short-form resolution wording should always name the deciding organ, quote the exact agenda item as noticed, state the vote count, and reference the specific bylaw or Civil Code article granting authority. Vague language (“the board approved the matter discussed”) is precisely the kind of record that unravels under later scrutiny. For deeds executed abroad or requiring recognition outside Italy, our guide on notarizing an Italian deed from abroad walks through the remote execution sequence step by step.
How Cerini Notary Office Supports Corporate Resolutions in Italy
Notarial services support international shareholders, boards, and legal representatives in executing Italian corporate resolutions correctly, from routine capital increases to bylaw amendments linked to cross-border transactions.
The firm’s relevant services include:
- Drafting and executing public deeds for extraordinary S.p.A. and S.r.l. resolutions, including bylaw amendments and capital changes.
- Producing legalized abstracts and apostilled documents for resolutions that need to be recognized outside Italy.
- Facilitating remote notarization for shareholders and directors who cannot travel to Italy for the signing.
- Assisting with transcription and filing at the Companies Register once a resolution is finalized.
- Preparing notarial powers of attorney so foreign shareholders can participate in meetings and sign resolutions without appearing in person.
- Managing escrow arrangements where a resolution triggers a related fund transfer, such as a share buyback or capital contribution.
For a cross-border client, the typical workflow starts with a review of the draft resolution and bylaws, moves to scheduling the notarial session (in person or remote), and closes with filing and issuance of any legalized extracts the client needs for use abroad. What distinguishes this process for international clients is that every step, from the initial consultation to the final filed deed, happens in English, removing the translation risk that causes so many governance mistakes among foreign-owned companies operating in Italy.
Do Public and Private Companies Follow Different Resolution Rules?
The S.p.A./S.r.l. divide covers most companies, but Italy also recognizes cooperative societies (società cooperative) and partnerships (società di persone, such as the S.n.c. or S.a.s.), each with its own decision-making logic.
Cooperatives generally apply a one-member, one-vote principle regardless of capital contribution, a sharp departure from the capital-weighted voting that governs S.p.A. and S.r.l. decisions. This changes the entire calculus for control and influence, something foreign investors evaluating a cooperative structure need to understand before committing capital.
Partnerships operate with even less formal machinery. Decisions in an S.n.c. or S.a.s. typically require unanimous partner consent for matters affecting the partnership agreement itself, though day-to-day management can often proceed on majority consent among managing partners, depending on how the partnership agreement is drafted. There is no equivalent to the shareholders’ meeting formalism, no mandatory minute-book transcription regime in the same sense, and notarial involvement is generally limited to the original partnership deed and subsequent amendments.
Listed S.p.A.s add a further layer beyond what privately held companies face: mandatory disclosure timing, market notification requirements, and closer alignment with Corporate Governance Code recommendations that a private company can safely ignore.
How Do Resolutions Affect Third Parties, and What Must Be Disclosed?
A corporate resolution rarely stays a purely internal matter. The moment it changes something third parties rely on, capital, representative powers, or the company’s registered purpose, disclosure obligations kick in.
Resolutions changing directors, share capital, or the corporate purpose must be filed with the Registro delle Imprese, and until that filing is completed, the change is generally not effective against third parties acting in good faith. This is why a buyer, lender, or counterparty checking a company’s public record before signing a contract is standard due diligence practice, not excessive caution.
Board resolutions delegating signing authority to a specific director also need to be reflected in the public register if that director’s power to bind the company is going to be relied on by outside parties. A contract signed by someone whose authority was revoked internally, but never updated in the public filing, can create real exposure for the company. This is one reason the 2026 governance reform tightened board duties around delegation limits, since unclear or unregistered delegation chains had become a recurring source of disputes in crisis situations. Creditors, potential investors, and counterparties in a merger or acquisition all rely on these filings being current, which makes prompt post-resolution registration a genuine risk-management step, not paperwork.
What Do Typical Corporate Resolutions Look Like in Practice?
Seeing how the rules apply to routine transactions makes the abstract framework concrete.
A capital increase to bring in a new foreign investor is an extraordinary S.p.A. resolution: the shareholders’ meeting approves the increase by qualified majority, a notary drafts the deed, and the new capital figure is filed with the Companies Register before the investor’s shares are formally issued.
A director appointment in an S.r.l. is usually an ordinary quotaholder decision, often handled through written consultation if the bylaws permit it, with the appointment then filed at the Companies Register so the new director’s signing authority is publicly recognized.
A merger between two Italian subsidiaries requires extraordinary resolutions from both companies’ shareholders, notarial deeds for each, and a filing sequence that runs through the Companies Register before the merger takes legal effect, often with a waiting period for creditor objections.
A change of registered office to a different Italian province typically counts as a bylaw amendment, an extraordinary matter needing a notarial deed, even though the practical change seems administrative. Cross-border shareholders handling this kind of resolution alongside a broader restructuring often coordinate it with related services like establishing an Italian company with foreign shareholders to keep governance and formation issues aligned.
How Much Control Do Company Bylaws Have Over Resolution Procedures?
The statuto is where the Civil Code’s default rules meet a specific company’s actual governance design, and the gap between the two is often wider than founders expect when they first review boilerplate articles of association.
Bylaws can raise quorum and majority thresholds above the statutory minimum, reserve additional matters to shareholders that the law would otherwise leave to the board, restrict or expand delegation to managing directors, and set specific procedures for written consultation in an S.r.l. They can also define notice periods, proxy limits, and tie-breaking mechanisms for deadlocked votes, none of which the Civil Code prescribes in detail.
What bylaws cannot do is override mandatory law, such as the requirement for a notarial deed on extraordinary S.p.A. matters or the minimum protections owed to minority shareholders. This is precisely why reviewing a specific company’s statuto before assuming any statutory default applies is not optional due diligence, it is the starting point for any resolution analysis. A well-drafted statuto anticipated for cross-border ownership will typically also address remote meeting protocols and proxy mechanics explicitly, rather than leaving foreign shareholders to guess how the default rules apply to their situation.
Updating Governance After the 2024–2026 Reforms
Legislative Decree No. 47/2026 gave Italian companies a real reason to pull their bylaws and board regulations off the shelf and read them again. The decree placed governance models on more equal footing and tightened board duties around delegation, particularly in crisis scenarios where unclear authority chains had previously caused real damage.
Boards should treat this as the moment to reassess two things specifically: whether the chosen governance model still fits the company’s ownership structure, and whether delegation clauses granting authority to a managing director or committee still comply with the sharper limits Articles 2380 and 2381-bis now impose. Bylaws written five or ten years ago rarely anticipated the crisis-decision rules the reform introduced.
Practical priorities include updating conflict-of-interest disclosure protocols, formalizing electronic meeting procedures that were previously handled informally, and clarifying which crisis-response decisions require full board involvement rather than delegated authority. Any of these updates that touch the bylaws themselves will need a notary to execute the amendment as a public deed, so it is worth bundling several governance updates into a single extraordinary session rather than returning to the notary repeatedly for incremental fixes.
— team
Ready to Formalize Your Company’s Next Resolution in Italy?
Getting a corporate resolution legally correct in Italy is not the place to improvise, particularly when shareholders or directors are based outside the country and cannot easily coordinate with a local notary on short notice. Foreign shareholders can benefit from notarial deed, power of attorney, and filing services with full English-speaking support, avoiding reliance on translated summaries of documents.
Whether the matter is an extraordinary capital increase, a bylaw amendment tied to a governance update, or a cross-border shareholder decision that needs a legalized abstract for use abroad, the firm’s company incorporation services cover the formation and statutory amendment work end to end, and remote notarization means a shareholder in New York or London can execute a valid Italian deed without booking a flight. For matters involving delegated signing authority or fund movements tied to a resolution, the notarial powers of attorney and escrow services round out what a cross-border transaction typically needs.
If you have a specific resolution to draft, a bylaw amendment to formalize, or a governance update to bring into line with the 2026 reforms, reach out directly to Cerini Notary Office at ngcerini@notaryinitaly.com for a consultation on your case.
Authoritative Primary Sources and Practice Notes
The statutory and case-law framework behind this guide draws on the Italian Civil Code company law excerpts covering default quorums and majorities, the Court of Milan’s 2025 ruling on transcription and challenge timelines, and the Mondaq analysis of Legislative Decree No. 47/2026. Governance benchmarking comes from the ICLG Corporate Governance guide for Italy and the OECD Corporate Governance Factbook 2025 Italy country note. Practice-level procedural detail is drawn from Practical Law’s coverage of S.p.A. general meetings. For company-specific questions, Notaryinitaly’s incorporation services can guide formation and amendment filings.
Sources
- Corporate Governance Laws and Regulations 2026 | Italy — ICLG
- Italy rewrites the governance rulebook for S.p.A.s — Mondaq
- OECD Corporate Governance Factbook 2025 — Italy country note
- Chambers insight on arbitration usage in Italy
- Court of Milan analysis — transcription and challenge timelines
FAQ
What Is the 7% Rule in Italy?
It has no application to corporate resolutions, quorum thresholds, or company voting procedures.
How Do I Get a Corporate Resolution Adopted in Italy?
Convene the appropriate body (shareholders, quotaholders, or the board) with proper notice, hold the vote, and record it in signed minutes with a full roll call. For extraordinary S.p.A. or S.r.l. matters like bylaw amendments or capital changes, a notary must draft the resolution as a public deed and file it with the Companies Register.
Is an Ordinary Resolution Passed by 50%?
The default rule for S.p.A. ordinary meetings requires presence of shareholders representing at least half the capital for quorum, with the resolution then passing by absolute majority of capital represented at the meeting, unless the bylaws set a different threshold. S.r.l. quotaholder decisions follow separate quota-based majority rules set out in the articles of association.
What Is the “Big 3” in Italy?
This phrase is not a recognized term in Italian corporate governance or company law and does not correspond to any statutory framework, resolution category, or governance standard covered here. If you encountered it in a different context, it likely refers to something outside Italian corporate resolutions entirely.
When Is a Notary Required for a Corporate Resolution in Italy?
A notary is required to draft a public deed for extraordinary S.p.A. or S.r.l. resolutions, including bylaw amendments, capital increases or reductions, and mergers. Ordinary resolutions, such as approving financial statements or appointing directors, generally only require signed minutes and, where applicable, filing with the Companies Register.
Can a Corporate Resolution in Italy Be Challenged After It Is Adopted?
Yes, through annullability (for procedural defects, filed within a limited window after adoption or transcription) or nullity (for more serious defects, with longer time limits). A resolution left untranscribed in the libri sociali never starts its challenge clock, as the Court of Milan clarified, leaving it exposed indefinitely.
Recommended
- Foreign Shareholder Rights in Italy Explained
- How to Transfer Italian Shares in an Italian Company
- Company Setup With US Shareholders in Italy
- Italian Company Formation Foreign Shareholders
The information provided here is general in nature and does not replace professional assistance. Reading this content does not create a professional-client relationship.